Does Adding a Parent Raise My Car Insurance
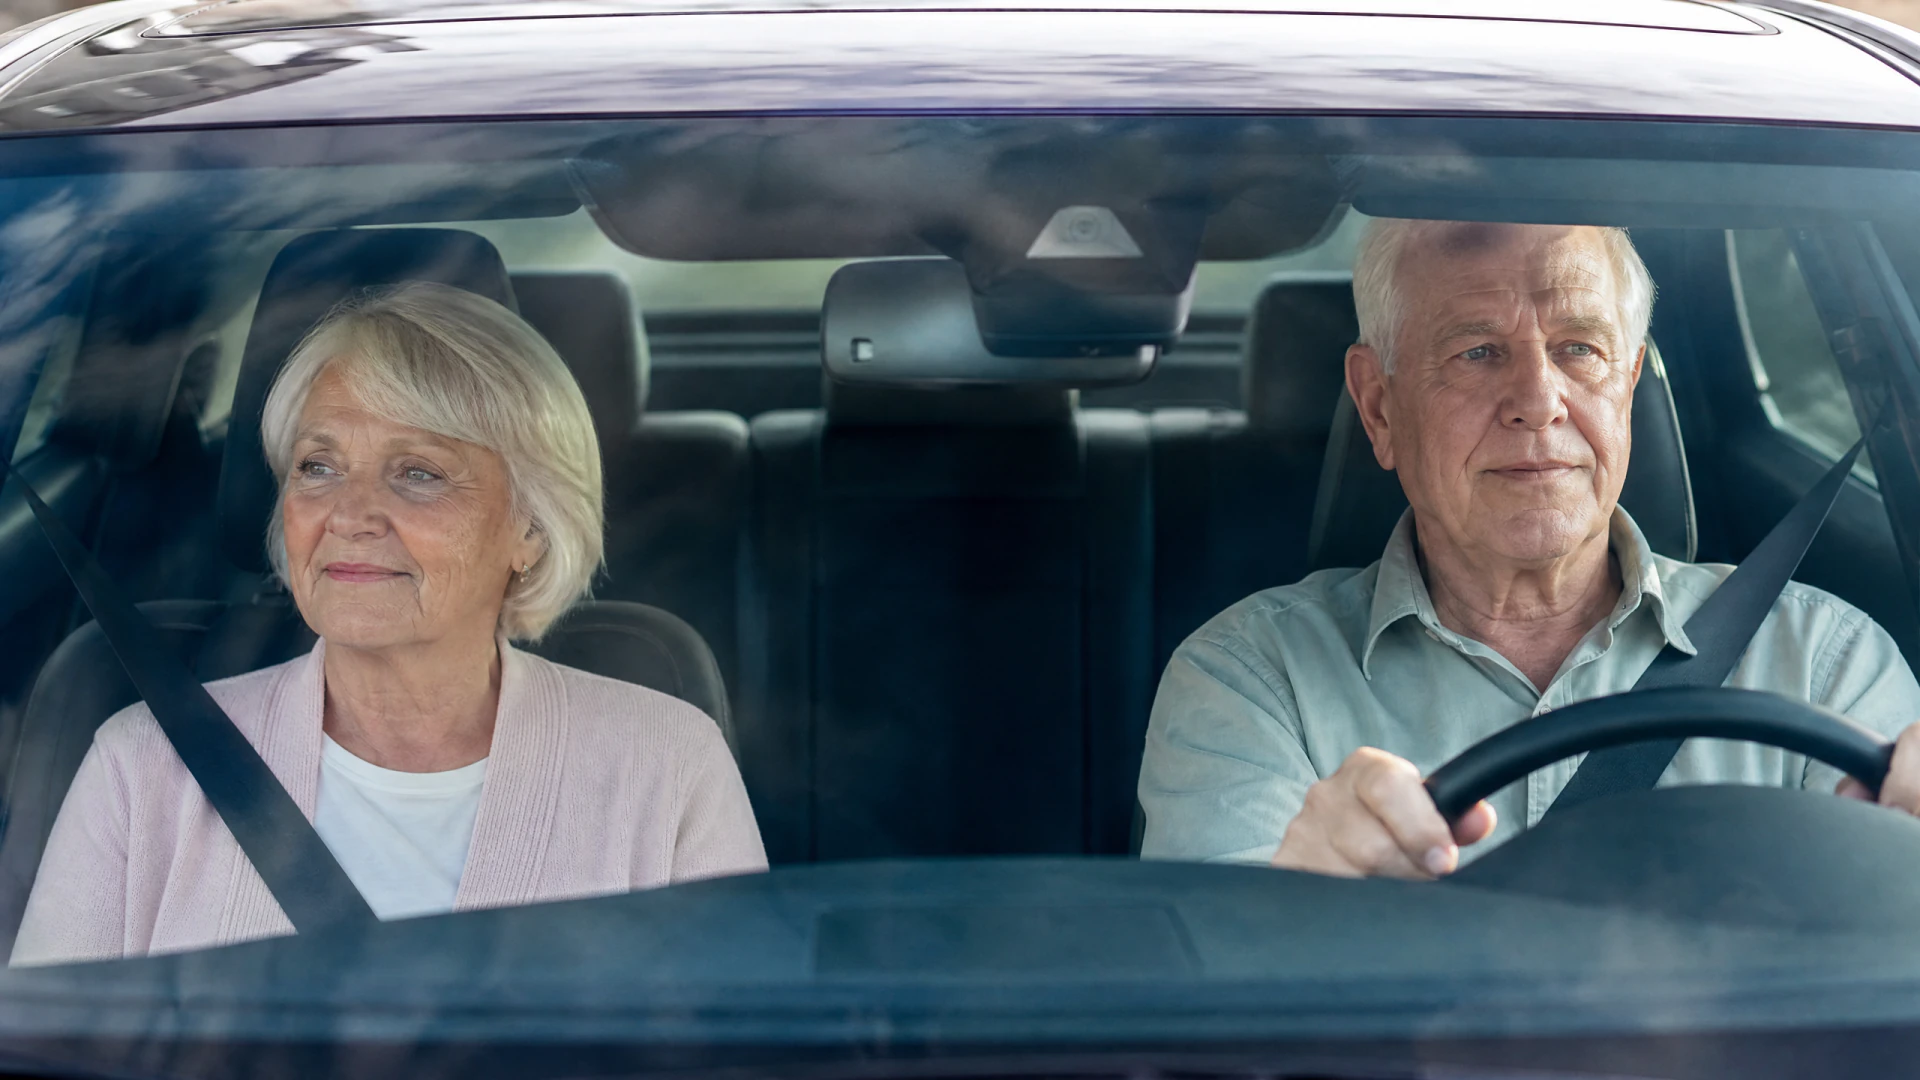
Adding a parent usually raises your premium, because insurers price the policy around the oldest and the riskiest driver on it.
Free to compare
Yes, in most cases it raises your premium
Adding a parent to your policy usually increases what you pay. Insurers price a policy based on everyone listed on it, and an older driver, especially one with a lapse in coverage, a health condition that affects driving, or a recent accident, can push the premium up even though you're the one who owns the policy.
How much it moves depends on your parent's own driving record, their age, and your insurer's rules for rating multiple drivers on one car. Some insurers rate the policy on the highest-risk driver. Others blend the risk across everyone listed. Ask your insurer directly how they'd handle it before you add your parent, so you know what you're agreeing to.
Your parent's driving record matters more than their age alone
An older driver with a clean record and a current license often adds less to the premium than people expect. Age by itself isn't the main problem. What raises the cost is a recent accident, a ticket, a gap in coverage, or anything in their history that signals risk to the insurer.
If your parent hasn't driven in years, or let their own policy lapse, that lapse itself can matter. Insurers often treat continuous coverage as a sign of lower risk, and a break in it can work against you even if your parent never had a claim.
If a doctor or the DMV has raised concerns about your parent's vision, reaction time, or medical fitness to drive, that can factor in too. Ask your insurer what they'd need to see, a recent eye exam, a doctor's note, or nothing at all, before assuming the worst.
Before you add your parent, ask them for their current driving record and how long they've been continuously insured. Bring that to your insurer and ask for a specific number, not a general answer.
Why your parent is going on your policy changes the outcome
If your parent is going to drive your car regularly, most insurers want them listed, and leaving them off can put a claim at risk if they're ever behind the wheel when something happens. In that case, the premium increase is the cost of being covered correctly.
If your parent rarely drives your car, ask your insurer whether an occasional driver costs less to add than a regular one. Some insurers have a lower rate for someone who drives a handful of times a year, and listing them that way instead of as a primary driver can keep the increase smaller.
If the real goal is to get your parent insurance because their own policy is expensive or hard to get, ask whether it's cheaper for them to carry a separate policy, even a minimal one, than to join yours. The answer depends on their record and your insurer's rules, so ask for both numbers side by side.
Questions people ask about this
Does adding a parent to my policy count as them owning the car?
No, adding someone as a driver doesn't make them an owner. Ownership is tied to the title and registration, not to who's listed on the insurance policy. If your parent is going to own or co-own the car, that's a separate step with the DMV, not something the insurance company handles.
Can I add my parent just to help them get coverage without them driving my car?
Ask your insurer directly, because this varies by company. Some insurers allow a named driver who doesn't regularly use the car, others expect everyone listed to actually drive it, and listing someone who won't ever drive the car can create problems if a claim is ever reviewed.
Will removing my parent later lower my premium back down?
Usually, yes, once they're off the policy the rating goes back to reflecting just the drivers who remain. Ask your insurer whether removing a driver takes effect immediately or at your next renewal, since the timing can affect when you see the change.
Does my parent's out-of-state license affect adding them to my policy?
It can, and it depends on your state and your insurer's rules for out-of-state licenses. Some insurers want the driver licensed in the state where the car is registered. Ask your insurer what they require before you add a parent who's licensed somewhere else.
Is it cheaper to put my parent on a separate policy instead of mine?
It depends on their driving record and how your insurer rates multiple drivers on one policy. Ask your insurer for a quote both ways, your parent added to your policy and your parent on their own policy, so you can compare the actual numbers instead of guessing.
See what adding your parent would actually cost before you decide.
Call your own insurer and ask them directly how adding your parent would change your premium, and whether they'd rate your parent as a regular or occasional driver. Have your parent's driving record and proof of their current or most recent insurance on hand, since the insurer will likely ask for it. If your parent rarely drives your car, ask specifically about an occasional driver rate instead of accepting the standard one. If the real goal is getting your parent covered rather than sharing your car, ask for a quote on a separate policy for them too, so you can compare the two options side by side. Get the numbers in writing before you add anyone to your policy.


